Technology
“I needed something with a simple interface for the end user. Mangue came in with an eye for simplifying, with other ways to get to the data, it helped a lot.”

Edvania Silva
ESG Manager · Hotmart
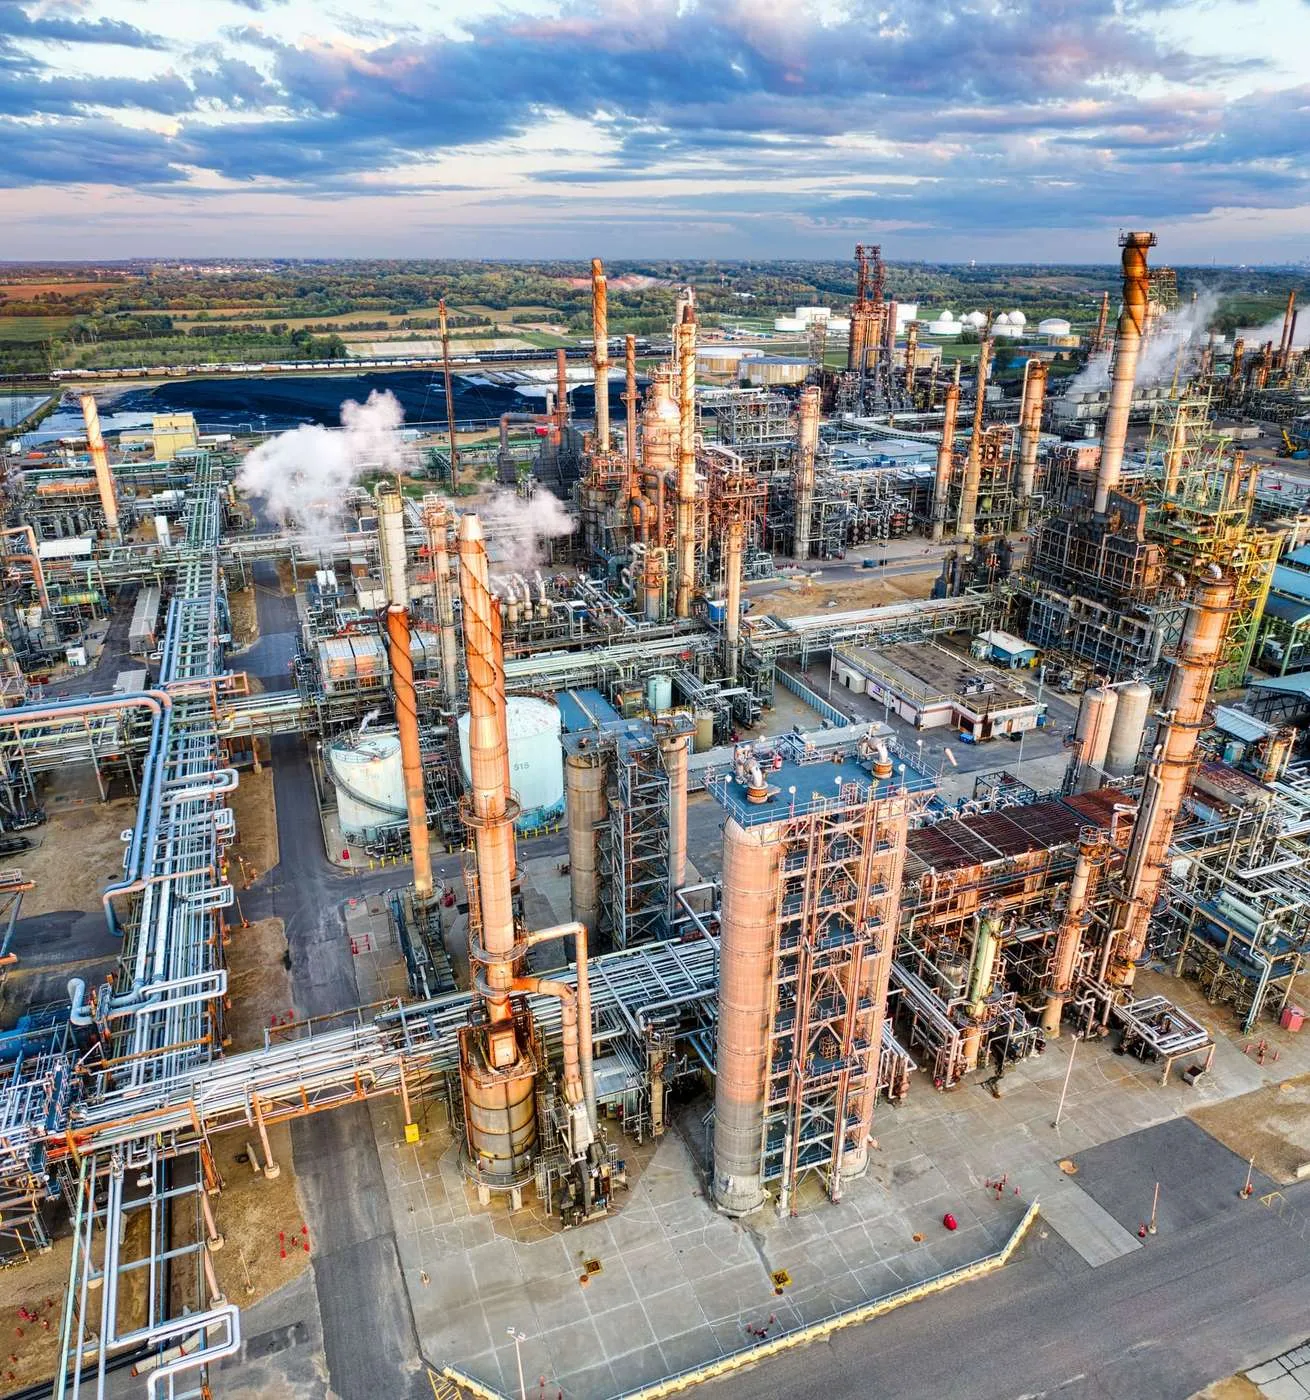
Identify the topics that matter to investors and the material impacts on society and the environment. Grounded in CSRD, GRI, IFRS S1/S2 and CVM 193.
Companies that trust Mangue Tech
Consulting + Platform
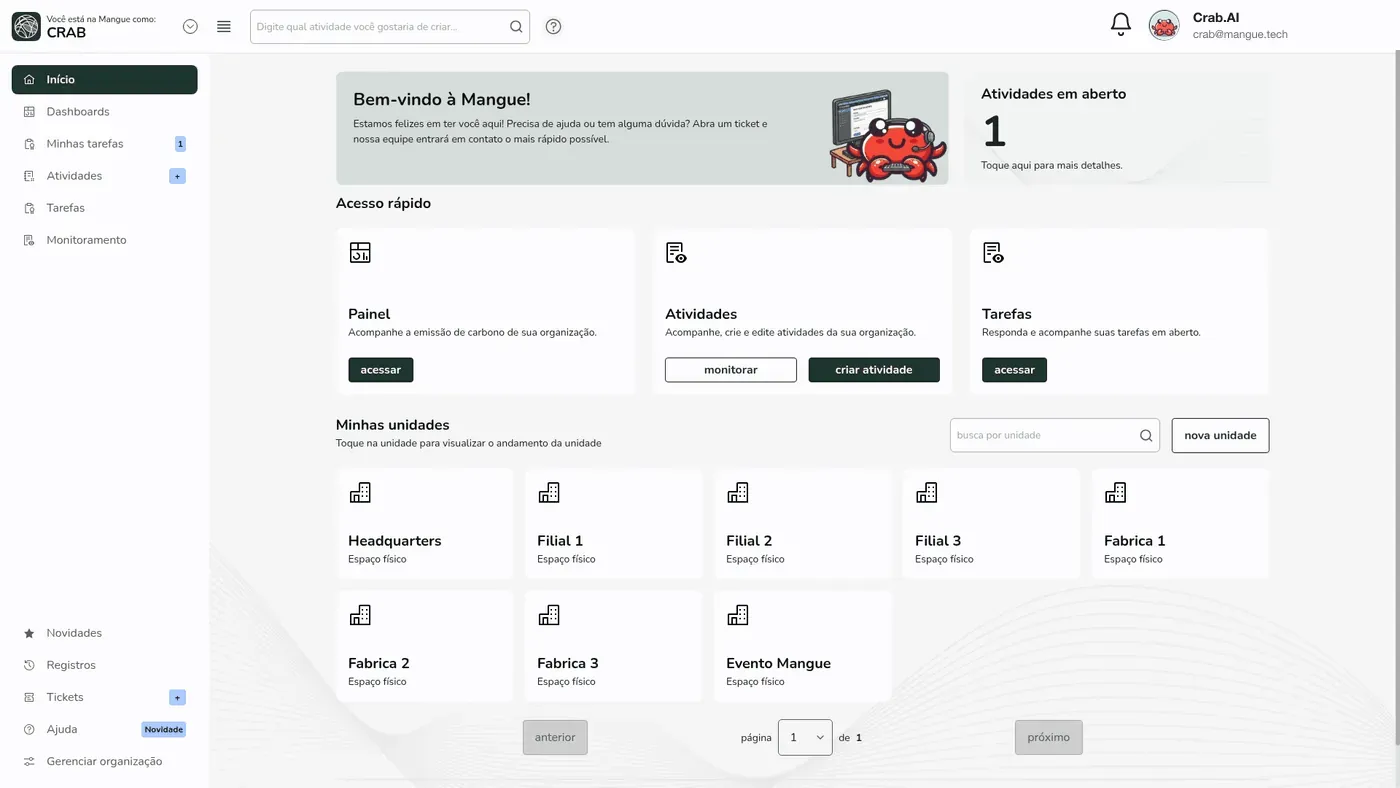
Specialist consulting that understands ESG materiality. A platform that automates the calculation, versions the data and exports it in the format the regulator requires.
ESG data and compliance management, with a specialist who knows your sector.
Our own software, automating calculations, indicators and exports.
GHG inventory, decarbonization plan and reports ready for the auditor.
Less time
Automated collection vs. manual spreadsheet.
Global frameworks
IFRS, CSRD, CBAM, GRI, SASB, GHG, CDP…
Emission factors
IPCC, DEFRA, MCTI, EPA, Ecoinvent.
How Mangue works
Find out which ESG risks affect your business and what the regulator will require.
Organized data, defined processes and everything ready for any verification.
Emission calculations, decarbonization targets and continuous monitoring.
Active compliance with IFRS, CSRD, CBAM, GRI, SASB and GHG Protocol.
Mangue deliverables for ESG materiality
Every delivery is a complete package: consultant + platform + auditable report. Click to see how we apply it.
The service
A materiality analysis is the exercise of identifying and prioritizing the ESG topics that matter to your company. Without a consistent matrix, sustainability reporting turns into a list of good intentions: no investor trusts it, no stakeholder recognizes it.
For public companies in Brazil, CVM Resolution 193/2023 requires reporting aligned with IFRS S1/S2 from fiscal year 2026 on, financial materiality. For companies with a European parent or European clients, CSRD/ESRS requires double materiality (impact plus financial) with limited assurance. Without well-grounded materiality, you pass neither.
We deliver a prioritized matrix of 8 to 12 topics (not 30), with a documented methodology, evidence of stakeholder engagement and a rationale for each topic. The auditor reads it and accepts it. The investor reads it and understands it. The internal team uses it to prioritize.
Delivery
Etapa 01
Topic universe: we cross GRI Standards, ESRS E1-E5/S1-S4, SASB for your industry, IFRS S1/S2 and a benchmark of 3 to 5 global peers. Typically 24 to 30 initial candidates.
Etapa 02
Stakeholder engagement: structured surveys (investors, clients, suppliers, employees), interviews with leadership and community workshops where they apply. No bias, with a defensible sample.
Etapa 03
Prioritization and matrix: quantitative plus qualitative analysis, classified into impact materiality (outside-in) and financial materiality (inside-out). We deliver the matrix, the documented methodology and the evidence folder.
Users comment
Technology
“I needed something with a simple interface for the end user. Mangue came in with an eye for simplifying, with other ways to get to the data, it helped a lot.”
Textile industry
“Today we can say we have consistent, organized data that lets us keep improving going forward. That's the platform's main role: giving us visibility into something that wasn't visible to everyone before.”

Frameworks involved
By industry
Frequently asked questions
Diagnostics, scope and proposal on the same day. Straight with the specialist who will run the project.