IFRS S2: climate financial reporting as the reference standard
Voluntary adoption in Brazil after CVM 244. It remains the standard required by investors, banks and global clients. Mangue Tech structures the disclosures on governance, strategy, risk management and metrics.
Companies that trust Mangue Tech
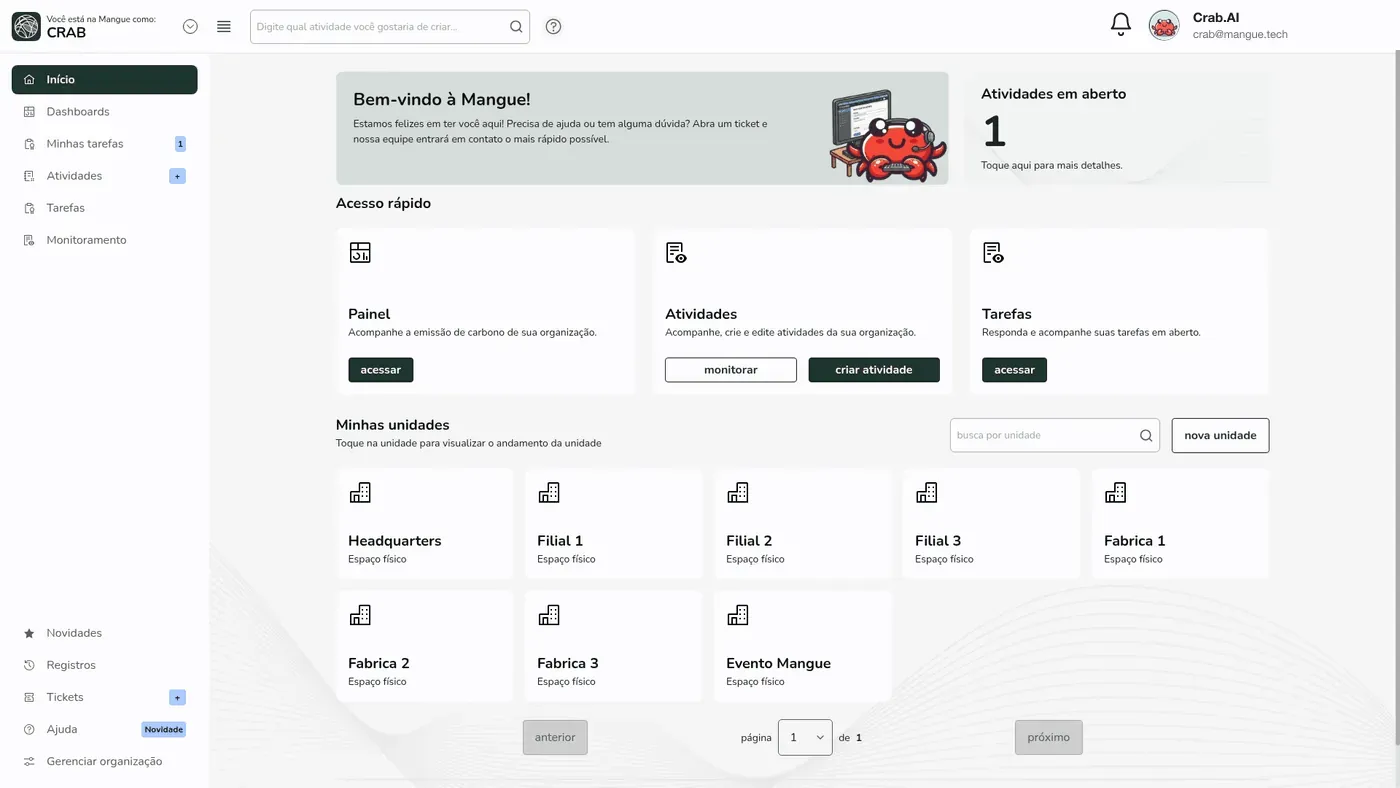
Consulting + Platform
Operational data becomes auditable ESG indicators.
Specialist consulting that understands IFRS S2. A platform that automates the calculation, versions the data and exports it in the format the regulator requires.
Consultoria
ESG data and compliance management, with a specialist who knows your sector.
Plataforma
Our own software, automating calculations, indicators and exports.
Auditable reports
GHG inventory, decarbonization plan and reports ready for the auditor.
Less time
Automated collection vs. manual spreadsheet.
Global frameworks
IFRS, CSRD, CBAM, GRI, SASB, GHG, CDP…
Emission factors
IPCC, DEFRA, MCTI, EPA, Ecoinvent.
How Mangue works
4 steps. From diagnosis to an auditable report.
Diagnosis
Find out which ESG risks affect your business and what the regulator will require.
Estrutura
Organized data, defined processes and everything ready for any verification.
Operation
Emission calculations, decarbonization targets and continuous monitoring.
Auditable reports
Active compliance with IFRS, CSRD, CBAM, GRI, SASB and GHG Protocol.
Mangue deliverables for IFRS S2
Every delivery is a complete package: consultant + platform + auditable report. Click to see how we apply it.
The framework
What it is, and why it matters.
IFRS S2 (Climate-related Disclosures) is the standard issued by the International Sustainability Standards Board (ISSB) for climate-related financial disclosures. In Brazil, CVM 193/2023 established adoption of the standard; CVM 244 revised the timeline and made adoption voluntary.
The standard organizes disclosures into four pillars: Governance (how the company oversees climate risks and opportunities), Strategy (current and projected impacts on the business model), Risk Management (identification and mitigation processes) and Metrics and Targets (GHG emissions, quantified transition and physical risks).
IFRS S2 absorbed the TCFD recommendations and uses SASB as its reference for industry metrics. Companies already reporting TCFD or SASB have a head start when moving to the standard.
At scale
When the standard updates, the calculation engine is already up to date.
supported frameworks
GHG Protocol, CSRD, IFRS S2, CDP, GRI, SASB, CBAM, SBCE. One single database.
emission factors
IPCC, DEFRA, MCTI, EPA, Ecoinvent. All versioned, with source, year and gas.
scopes covered
Scopes 1, 2, 3 and biogenic. Operational and financial. Everything goes in.
Aplicabilidade
Who it applies to.
- Brazilian listed companies that want to adopt IFRS S2 voluntarily. It signals ESG maturity to the market and prepares them for the next regulatory round.
- Companies under pressure from investors, banks or international funds for climate financial disclosure aligned with IFRS.
- Organizations that already report TCFD and need to migrate to the IFRS S2 format, with adjustments to scope and granularity.
How we deliver
From source to auditor.
We map the company's current disclosure (TCFD, CDP, integrated report) and identify the gaps against the IFRS S2 requirements.
We structure the disclosures across the four pillars, combining quantitative emissions data (the Mangue platform) with qualitative governance and strategy information.
We deliver the IFRS S2 disclosure draft ready for review by the independent auditor, with industry SASB mapping and cross-reference to CDP.
The IFRS S1 & S2 Roadmap: the 12 decisions your CFO must make before 2027
A practical guide for CFOs, IR Directors, Controllers and Accounting. ~15 min read, straight to your inbox.
We got your info! Camila will send you the IFRS S1 & S2 Roadmap by email shortly.
Perguntas frequentes